FAST-DS 2026: Verified Guide to India’s Foreign Asset Disclosure Scheme
Foreign asset reporting can become complicated when a taxpayer discovers that an overseas bank account, shares, ESOPs, securities, insurance policy or other foreign asset was not properly disclosed in the relevant income-tax return.
If you are searching in Ghaziabad, Noida, Delhi NCR and nearby areas for a Tax consultant near me, Income tax consultant near me, or professional guidance on foreign asset disclosure, understanding FAST-DS 2026 is important before taking any action.
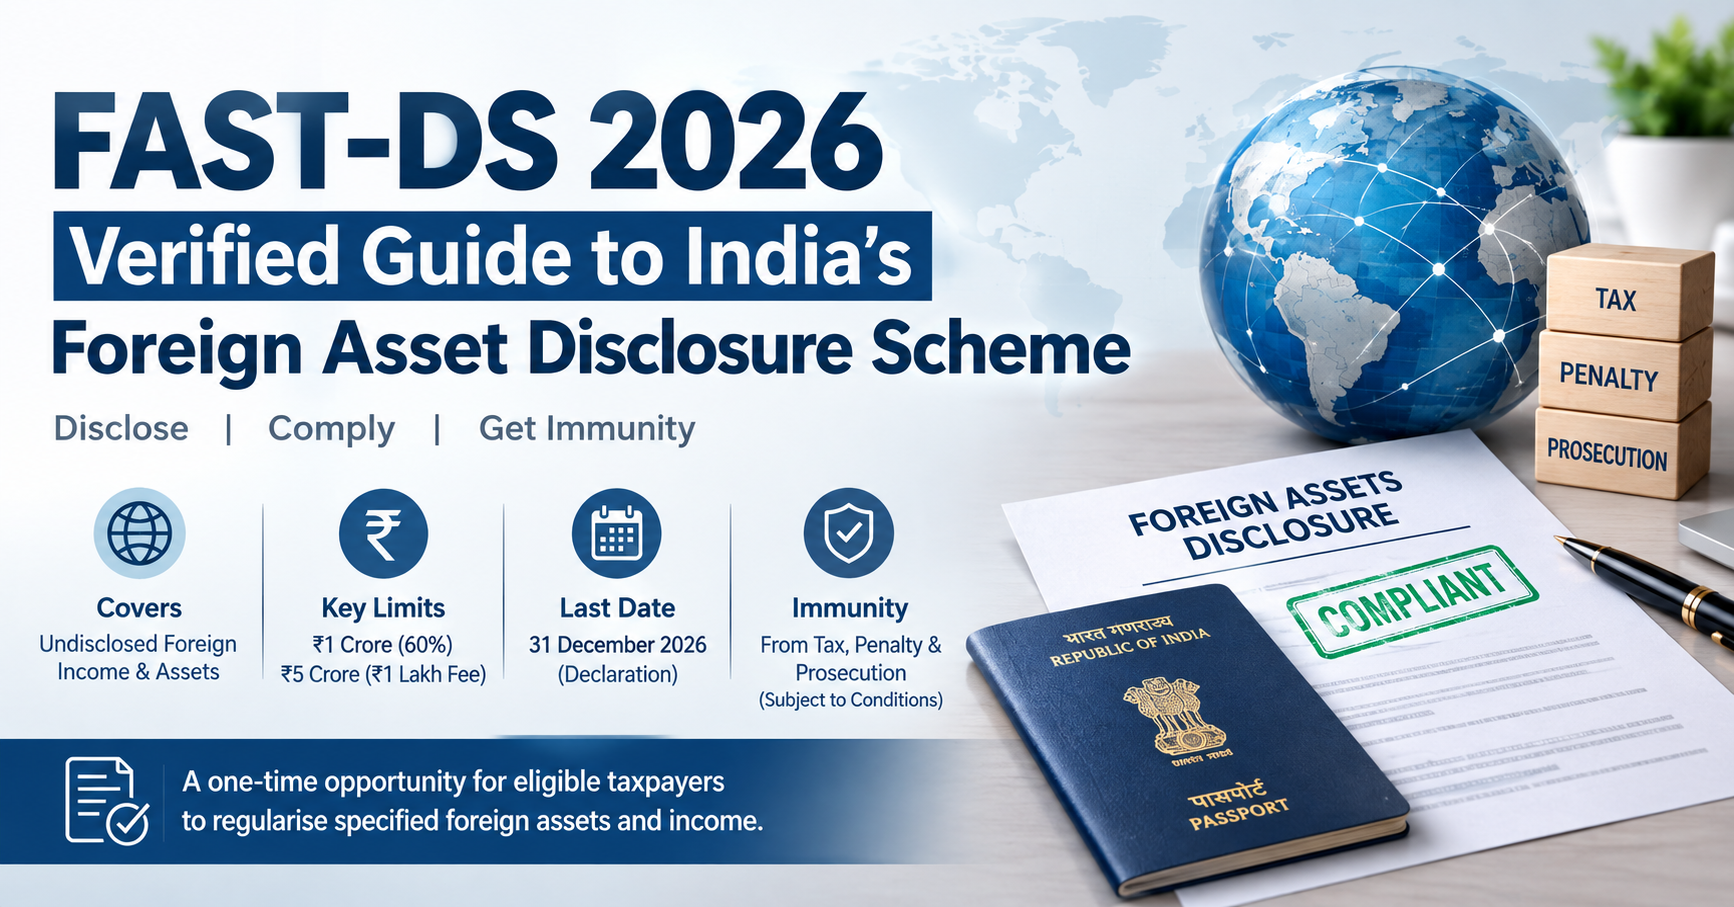
The Government of India has introduced the Foreign Assets of Small Taxpayers–Disclosure Scheme, 2026, commonly referred to as FAST-DS 2026. It provides a one-time opportunity to eligible taxpayers to disclose specified foreign income and assets that were either not offered to tax or were not reported in the relevant income-tax return schedule.
A valid declaration, followed by payment of the prescribed tax or fee, may provide immunity from further tax, penalty and prosecution under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, subject to the conditions and exclusions prescribed under the Scheme.
The Central Board of Direct Taxes has also notified the rules and prescribed forms through Notification No. 114/2026, dated 1 September 2026.
Latest Update
As of 1 October 2026, FAST-DS 2026 provides a one-time disclosure mechanism for eligible taxpayers having specified undisclosed foreign income or assets, or specified foreign assets that were not reported in the relevant return schedule.
The principal deadline for making the declaration is 31 December 2026. Payment and subsequent compliance are subject to separate timelines after the determination order.
The Scheme should not be treated as an automatic settlement facility. Eligibility, valuation, residential status, source of funds and other prescribed conditions must be examined based on the taxpayer's individual facts.
Legal Reference
Section / Law: Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, and provisions applicable to the Foreign Assets of Small Taxpayers–Disclosure Scheme, 2026.
Rules / Notification: CBDT Notification No. 114/2026, dated 1 September 2026.
Official Source Links:
https://www.incometax.gov.in/iec/foportal/latest-news/11933
Legal Position
The Government of India has introduced the Foreign Assets of Small Taxpayers–Disclosure Scheme, 2026, commonly referred to as FAST-DS 2026. It provides a one-time opportunity to eligible taxpayers to disclose specified foreign income and assets that were either not offered to tax or were not reported in the relevant income-tax return schedule.
A valid declaration, followed by payment of the prescribed tax or fee, may provide immunity from further tax, penalty and prosecution under the Black Money (Undisclosed Foreign Income and Assets) and Imposition of Tax Act, 2015, subject to the conditions and exclusions prescribed under the Scheme.
The Scheme may apply to a person who is or was resident in India during the relevant period and satisfies the prescribed conditions. This may include a person who is currently a non-resident or resident but not ordinarily resident if that person was resident in India when the foreign income accrued or when the foreign asset was acquired.
Potentially relevant cases may include employees holding foreign ESOPs or RSUs that were not reported, individuals retaining dormant or low-balance foreign bank accounts, returning non-residents holding undisclosed foreign savings or insurance policies, and persons who acquired foreign assets from income already disclosed and taxed in India but omitted the assets from the relevant return schedule.
FAST-DS covers undisclosed foreign income, undisclosed foreign assets and specified foreign assets not reported in the return. These may include foreign bank accounts, shares, securities, financial interests, immovable property and other eligible overseas assets.
The applicable limit and payment depend on the category of foreign asset or income.
|
Category |
Monetary limit as on 31 March 2026 |
Amount payable |
|
Undisclosed foreign asset or undisclosed foreign income |
Up to ₹1 crore in aggregate |
30% tax plus an additional amount equal to 100% of that tax; total 60% |
|
Foreign asset acquired from disclosed income or during non-resident status but not reported |
Up to ₹5 crore |
Fixed fee of ₹1 lakh, subject to conditions |
For an undisclosed foreign asset or foreign income valued at ₹50 lakh, the total amount payable under the 60% mechanism would generally be ₹30 lakh, subject to the Scheme's valuation and eligibility provisions.
For the second category, the ₹1 lakh fee is generally payable once for the same asset where the asset remained undisclosed for multiple years. Separate assets acquired in different years may attract separate fees in accordance with the prescribed rules.
The declaration process is electronic. The taxpayer must identify the foreign asset or income, determine the relevant category, verify residential status, determine the value as on 31 March 2026 under the prescribed valuation rules, submit the prescribed declaration electronically, await the order determining the amount payable, make payment through ITNS 289, submit the prescribed intimation with proof of payment and obtain the electronic certificate confirming payment under the Scheme.
The amount determined is generally payable within two months from the end of the month in which the order is received. A further extension of up to two months may be available, with simple interest at 1% for every month or part of a month on the unpaid amount. If payment is not completed within the permitted period, the declaration may become void.
A declarant who makes a valid declaration and pays the prescribed amount may receive immunity from tax, penalty and prosecution under the Black Money Act in respect of the income or asset covered by the declaration.
However, immunity is conditional. It may not be available where the declaration contains false information, material misrepresentation or suppression of facts; the asset or income represents proceeds of crime under the Prevention of Money Laundering Act, 2002; assessment proceedings under the Black Money Act have already been completed; or the taxpayer fails to pay the amount within the prescribed period.
Taxpayers should also review bank records, demat statements, foreign tax documents, acquisition documents, remittance records, previous income-tax returns and relevant Schedule FA disclosures before making a declaration.
Taxpayers should not rely only on the regular AIS while reviewing foreign assets. The absence of an entry on the portal does not by itself establish that an asset is compliant. Similarly, the presence of an information item does not automatically establish taxability or eligibility under FAST-DS. The taxpayer must independently reconcile the information with the underlying documents and income-tax returns.
Practical Explanation of FAST-DS 2026
In simple terms, FAST-DS 2026 is relevant where a taxpayer has a specified foreign asset or income that requires correction or disclosure and the prescribed conditions are satisfied.
For example, an employee may have received foreign RSUs while working for an international company but failed to report the relevant foreign asset in the applicable return schedule. Another taxpayer may have maintained a foreign bank account that was omitted from the return even though the underlying funds came from income already disclosed and taxed in India.
The treatment can differ depending on the source of funds, residential status, nature of the asset and whether the income was previously disclosed.
|
Issue |
What should be checked? |
|
Foreign bank account |
Ownership, balance, source of funds and Schedule FA reporting |
|
Foreign shares/ESOPs/RSUs |
Acquisition details, income treatment and reporting |
|
Foreign property |
Ownership, acquisition cost, source and prescribed valuation |
|
Previously disclosed income |
Whether the foreign asset was acquired from income already offered to tax |
|
Residential status |
Status during the relevant period when income accrued or asset was acquired |
|
Prior proceedings |
Whether assessment proceedings under the Black Money Act have already been completed |
For taxpayers looking for Income tax services near me or professional assistance in Ghaziabad, Vaishali, Indirapuram, Vasundhra, Noida or Delhi NCR, the practical focus should be on document reconciliation rather than relying on a portal alert alone.
Step-by-Step Compliance Process
Step 1: Identify the foreign asset or income.
Prepare a complete list of foreign bank accounts, securities, shares, ESOPs, insurance policies, properties and other overseas interests.
Step 2: Check residential status.
Review the taxpayer's residential status for each relevant period because eligibility can depend on the status when the foreign income accrued or asset was acquired.
Step 3: Establish the source of funds.
Determine whether the asset was acquired from income already disclosed in India, undisclosed income or another source.
Step 4: Review previous returns.
Check relevant income-tax returns and Schedule FA disclosures to determine what was and was not reported.
Step 5: Determine valuation.
Calculate the value as on 31 March 2026 according to the prescribed valuation provisions.
Step 6: Check exclusions.
Review whether there has been a completed Black Money Act assessment, whether the declaration could involve prohibited proceeds of crime, and whether all information can be truthfully verified.
Step 7: Submit the electronic declaration.
Complete the prescribed declaration and verification electronically.
Step 8: Pay the determined amount.
After receiving the order, make payment through ITNS 289 within the prescribed period.
Step 9: Submit payment intimation.
Provide the prescribed intimation along with proof of payment.
Step 10: Preserve the certificate and records.
Maintain the electronic certificate and supporting documents for future compliance and record purposes.
Particular care is required while making payment because payments made under an incorrect minor head cannot be corrected or refunded through the prescribed facility.
FAQ
1. What is FAST-DS 2026?
FAST-DS 2026 is a one-time disclosure mechanism for eligible taxpayers concerning specified undisclosed foreign income and assets, as well as certain foreign assets that were not reported in the relevant income-tax return schedule.
2. What is the main deadline for FAST-DS 2026?
The principal deadline for making the declaration is 31 December 2026. Payment and later compliance follow separate prescribed timelines after the determination order.
3. Is every foreign asset automatically eligible?
No. Eligibility depends on the prescribed conditions, including the nature of the asset, residential status, source of funds, reporting history and applicable exclusions.
4. What is the ₹1 crore limit?
For undisclosed foreign assets or undisclosed foreign income, the stated monetary limit is up to ₹1 crore in aggregate as on 31 March 2026, with the applicable amount payable being 30% tax plus an additional amount equal to 100% of that tax, resulting in a total of 60%, subject to the Scheme's provisions.
5. What is the ₹5 crore category?
Certain foreign assets acquired from disclosed income or during non-resident status but not reported may fall within the category having a monetary limit of up to ₹5 crore, with a fixed fee of ₹1 lakh, subject to the prescribed conditions.
6. Does an AIS entry automatically mean FAST-DS applies?
No. The presence of information in AIS or another reporting platform does not automatically establish taxability or eligibility. The information should be reconciled with underlying documents and previous returns.
7. What happens if the declaration contains incorrect information?
Immunity is conditional and may not be available where the declaration contains false information, material misrepresentation or suppression of facts.
8. Can professional assistance help with foreign asset disclosure?
Yes. A tax professional can assist with reviewing residential status, source of funds, foreign asset records, Schedule FA reporting, valuation, eligibility and the prescribed declaration and payment process.
Conclusion
FAST-DS 2026 provides an official one-time disclosure mechanism for eligible taxpayers with specified undisclosed foreign income or assets, or foreign assets omitted from the relevant return schedule. Because the consequences of an incorrect declaration can be significant, taxpayers should review their records carefully before filing.
If you are located in Ghaziabad, Noida or Delhi NCR and are searching for Income tax consultant near me, GST consultant near me, Company registration consultant near me, Trade Mark consultant near me, or logo registration consultant near me, professional assistance can help ensure that the relevant documentation and compliance requirements are reviewed systematically. Similar searches for GST services near me, Company registration services near me, Trade Mark services near me, and logo registration services near me may also be relevant when broader tax and business compliance support is required.
FAST-DS should not be approached solely on the basis of an AIS entry or a general alert. Residential status, asset valuation, source of funds, Schedule FA reporting, prior proceedings and the availability of immunity should be examined case-by-case using the applicable Finance Act, notified rules, prescribed forms and official Income Tax Department guidance.
For expert guidance on this topic, contact your tax professional today.
This content is for educational and knowledge purposes only. For verification and applicability to your case, please consult your tax professional.
Have Questions? We're Here to Help
Get expert advice from AMIT SIDDHI AND ASSOCIATES. Reach out to discuss your requirements.